India’s electronics manufacturing story has two very different faces, and neither one looks quite like the other despite both operating under the same broad EMS umbrella. One makes the televisions and phones sitting in your living room. The other builds the air conditioners keeping that same room cool. Understanding what actually moves each business helps explain why their stocks tell such different stories.
From Living Room Screens to Cooling Units
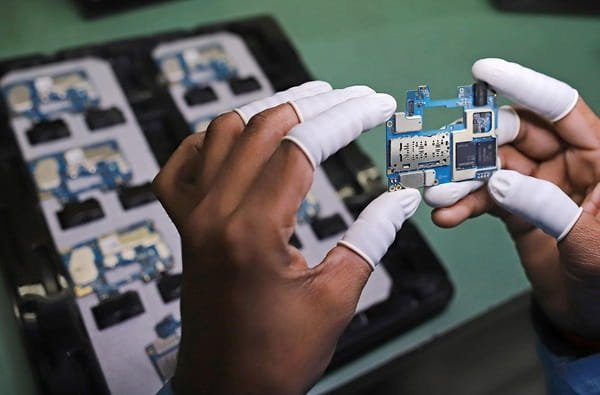
One of these companies has built itself into India’s largest consumer electronics contract manufacturer, producing LED TVs, washing machines, mobile phones, and set top boxes for brands like Samsung, Haier, and Xiaomi. The other has carved out a narrower but deeply specialized niche, focused almost entirely on manufacturing room air conditioners and their components for major names like Daikin, Voltas, and LG. Both companies benefit from the government’s PLI scheme tailwinds, but their actual business drivers barely overlap.
The Size Gap Nobody Can Ignore
With a market value of about ₹86,000 crore, the consumer electronics-focused company’s present size is over three times that of its air conditioning-focused competitor that is closer to ₹26,000 crore. To a large extent, this is explained by the larger basket of products that one offers versus a focused offering from the other.
The Cost of Betting Big on Expansion
Checking Amber share price movement means factoring in a company still working through an aggressive capacity expansion phase. The current price to earnings ratio for this company is significantly higher than 100, which is a far cry from what many may perceive it to be. The company’s near-term earnings aren’t particularly surprising given the heavy capital expenditure into new products as a percentage of their revenue. It isn’t a sign of a weak outlook but more related to R&D. Return on equity here currently sits under 5 percent, a number investors watching this stock should interpret through the lens of an expansion story still maturing, not a company underperforming its core business.
Efficiency Built Over Years, Not Overnight
On the other side, tracking Dixon share price reflects a business already operating at a considerably more mature stage of its growth curve. Return on equity here exceeds 30 percent, an exceptional figure for any EMS business, paired with a price to earnings ratio sitting meaningfully lower than its counterpart despite the larger overall market capitalization. This combination, high returns alongside a more reasonable valuation multiple, tends to reflect genuine operating efficiency across a diversified product mix rather than reliance on any single growth bet.
Borrowed Capital, Different Comfort Levels
Debt to equity ratios diverge meaningfully between the two as well. Considering the amount of capital expenditure currently underway for this company, it shouldn’t come as a surprise that it has a higher debt load than its competitor that has a much smaller product basket and, therefore, lower leverage. Not that either is a concern, but it is important to consider this when juxtaposing the two companies concerning earnings quality.
Two Bets, Not Two Rivals
These aren’t really competing stocks in the traditional sense, they’re two different bets on India’s broader electronics manufacturing buildout. One offers exposure to a mature, highly profitable, diversified consumer electronics business. The other offers exposure to a more concentrated, still expanding air conditioning specialist whose current thin earnings reflect investment rather than weakness. Investors weighing both should pay close attention to PLI scheme disbursements, new product category wins, and how margins evolve as capacity investments mature, rather than judging either purely on today’s price to earnings snapshot. As always, reviewing current data directly on the exchanges and consulting a SEBI registered advisor remains the sensible starting point before acting on either.